
[David] Let’s get over to Alice, get an update on the legislative happenings in the world. What you got, Alice?
[Alice] Hi, everyone. Dave, as you mentioned, and as the Mortgage Bankers Association bit talked about, is the VA bill, H.R.9237, that passed the House by a voice vote. So there’s a little bit of angst going on with that, that the Senate sent them a revision to look at. And while the bill that was getting looked at, they went for a voice vote on another version of the bill . So there was a little bit of stuff going on as to how that one passed so- Actually parliamentary but, politics aside on how it all went down, we did have a bill back in March on this that also passed that we talked about back then, or was it May, that is looking at increasing the VA IRRL interest rate reduction refinance loan fee- Right to compensate and pay for the veterans’ the money that it, they want to use to improve many veteran services. So as we’ve said, we’re all in favor of money that goes to expand veteran services. The bill that just passed the House has over $4 billion worth of increased expenses, ranging for VA technology, different medical facility authorizations, all things that we can all definitely get behind. The issue is that the money they want to have it come from VA refinance home loan borrowers. So today, if you have a VA loan and you wanna refinance just simply to get a lower payment, all it’s going to do is get your rate down, get your payment down. Those are the simplest loans in mortgage banking for us to roll over. There’s no change in risk for VA. They have the loan already. So the idea that we’re going to increase this fee so exponentially as they talked about increasing it from right now it’s only . 5% and increasing it up to 1.42%, which is going to change the cost to a veteran borrower by thousands, depending on the loan amount. So that’s a lot of money coming from the wrong place to fund these worthwhile endeavors. So that’s the issue … Everybody needs to- Amen I really think there needs to be a mo- I’m sorry, Dave. What’d you say? I just said amen. I can’t believe it Yeah, it’s just … yeah, it’s just- It’s ridiculous … and the estimates, yeah. I’m sorry. And the estimates that the CBO put in the bill, usually they look out about 10 years, put the numbers together, and say, “Okay, what’s this gonna cost the taxpayers over 10 years?” And they’re projecting that the VA IRRL fees will cover a substantial amount of this. We just got talking about rate increases. Where are refinances going to come from to pay this? So I don’t think the math is right, just me personally. No. And just kind of comparison and playing around with some AI scenarios on this. So I think that’s the issue, folks, is we all want something. Now, there is a companion Senate bill that’s out there as well as the House bill that we just talked about. 9237 is going to make its way over there. So nothing’s done yet, and they do have to act on this by the end of the year, otherwise it all gets thrown out in the wash and has to start all over again after January 3rd. So we will be watching this very closely, but I do urge everyone to reach out to their congressman. This is the simplest way to send it to them. Don’t increase the VA interest rate reduction refinance fee to pay for other veteran programs. Find another way to get that money. Thoughts from the group?
[Kittle] I’ll give you one. it absolutely underscores once again politicians making decisions around monetary decisions in businesses they know nothing about. It’s incredible.
[Bill] Yeah. So I totally agree. I think the other way that I would frame it is, we as a country owe the veterans. Why are they upgrading the VA on the back of the veterans and not the entire country.
[Alice] That’s a great point, right? They’re getting money from veterans out of the right hand to pay for it out of the left hand, and then this money isn’t gonna go towards actually supporting the VA home loan program itself, which, they need technology, they need staffing, they need certain things as well. One other thing hidden in that bill, by the way, is, as I mentioned, the CBO projects things out for usually about 10 years, depending on the program and the bill. In a previous bill, they… Right now we have that our current VA funding fees are due to increase in 2034, right? Which, believe it or not, is less than 10 years away. And now they’re saying in order to also fund this, they would have to not let the VA funding fee go down on our purchases. Right now it was budgeted to go down in 2034 back to where it was, ’cause it got increased to 2.15 several years ago, many years ago, and it’s scheduled to go down again, was the promise. Now this bill says, “Sorry, remember that promise we made before? Forget that. We’re gonna have to push that out to 2036.” So that’s another little hidden piece in here of getting more money from veterans to turn around and pay for veteran services
[David] Oh my gosh. The veterans have done so much for us. Why can’t we just be doing everything we can to help them? and rather than trying to take money from one pocket to pay another pocket.
[Kittle] Yeah, and I wouldn’t be surprised once it goes in there, it doesn’t get spent out of the VA program for something else. Yeah, out of the VA program, yeah. That’s we’re always, they’re dipping into that. Sad. Really sad. Good report, Alice. Thank you so much. all right, let’s get over to talking about production. Generally speaking, we’re still in continuing to hear that while production is off, it’s sliding. We’re seeing still some good reports of activity, Mr. Kittle.
[Kittle] Yeah. A lot to add to it, but that’s about right. Is it, again, it’s regional. Marc can opine that it may be horrible in Houston or wherever his other house is, but in some parts of the company- … it’s still steady production. But again, next week is Thanksgiving. I know it or in two weeks. We’re coming into the holidays. It typically slows. Yeah. That adds on higher interest rates, and I would just reiterate once again, go find a good ARM relationship, if you don’t, your borrower is. That’s right. It’s- Be, help your borrower. Yeah. Whether you get the loan or not, you don’t have an agreement or not, take care of your borrower, they’ll come back to you long term. Yeah. Sometimes- Even if you have to broker Yeah. Even if you have to broker it. Yeah.
[Bill] Yeah, and if you’re gonna go out and build those kind of relationships figure it out from both sides. It’s pretty easy as to why you as a lender needs the relationship, but figure it out from the other side. Why is it beneficial to community bank or a credit union, right? And it’s gotta be a fair value proposition or you’re just gonna be dialing for dollars. But put some effort into it and it can be successful.
[Bill] Yep, really good points like we said earlier, well worth the effort to build a relationship for a number of reasons. You may find yourself getting some referral business from them, ‘ cause they don’t wanna they may not have a lending division. So works very much both ways.
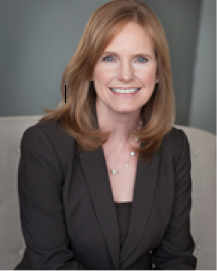
Alice Alvey, Master CMB
She handles development of their World Class Training program designed to support UHM partners and organizational effectiveness.
Prior to UHM, Alice served as Senior Vice President at Indecomm leading the Indecomm-Mortgage U division, Internal QA and Compliance and SaaS technologies. Indecomm acquired Mortgage U in 2013, where Alice was President/Co-founder, providing training and consulting since 1996. Prior to MU she served as SVP of Operations at a national bank overseeing operations for wholesale, retail and correspondent from underwriting through servicing, and compliance.
She has been in the trenches of mortgage lending operations from application through servicing for over 30 years. Her authoring work in training content, policies and procedures and the FHA/VA Practical guides illustrates her ability to bridge regulatory requirements with day-to-day operations.
Alice has been a weekly contributor to the Lykken on Lending show since its beginning in April 2009 and has made her weekly contributions to 450+ episodes!