
[David] Bill, good to have you here, man. You’re amazing. I love what you have done in our industry. You have s I I don’t think there’s anyone more qualified to talk about the topic that we are doing, non QM than you. So good to have you here, brother.
[Bill] Yeah. Hey, no, I’ve, I’ve lived my life and in non agency, I think and so I’m, I’m excited to talk about it because I think we can bring some light things, the light that actually I think people don’t think about. And because most of our industry is agency driven, I think it’s good for people, especially with rates where they are and where the world is at this moment. I think it’s actually going to be apropos. And I think most people are trying to figure it out anyway, so we can maybe get guidance.
[David] Well, I again like you said, there I don’t think anyone has been in it more than you, longer than you, and deeper than you. You went from originator, retail originator, all the way into, I mean, literally partnering with Merrill Lynch on and I mean, so I mean, you’ve lived the full journey of every aspect from originations to the deepest capital markets to MSR retention. So I’m really interested in starting, Bill, by giving our listeners a historical perspective on nonagency.
[Bill] Yep. You know, so I’m going to go back to 94, but you know, because I, when I moved from Ohio, I’m a Midwestern kid, went to law school at Santa Clara and started my business on Franklin street in Santa Clara. One of the first things that I learned about California is how unique it is.
[David] It is.
[Bill] But think about 1980, right? So 79, 80 interest rates double. So you’re sort of in this market that I’d never seen before as an Ohioan, right? So I think what I learned is the first thing in non-agency was jumbo. So most of the loans in California, most back then, because the conforming limits were really low, a lot of those loans were over the limit. So I was pushed into non-agency to start. The second thing…
[David] Yeah, you almost need to do that for survival.
[Bill] Well, you did. mean, you almost had to right now over time. A lot of the folks have been in the business recently, right? I think coming out of 07, 08, and then coming out of COVID, you had the limits artificially bumped so that the conforming limits are pretty high now. So there’s a little bit of change there, but I think the other piece that I learned is that, you know, as a result, a lot of people don’t qualify. A lot of people are pushing DTIs. A lot of people have different incomes. Most, most and a lot of California are very entrepreneurial. So we were early to, I think a lot of the pressures that are probably affecting the rest of the United States today, right? So my first foray, in fact, I met my wife, you know, Bev, I met my wife, she was.
[David] Yes, I know I I wanna celebrate first of all, just a little side note a little trick. I the marriage that you and Bev have is just amazing.
[Bill] Thank you.
[David] Amazing kids. Bobby Joe again over Total Expert. What amazing young lady that person is. Energy plus and just your whole family’s like that. You just
[Bill] No, thank you. We’re so blessed. I think Bev was Bruce Paradis’s executive.
[David] Yeah. For those who don’t know, Bruce was the CEO of RFC Residential Funding Corp.
[Bill] Probably the first non-agency conduit, right?
[David] Yep. Yep.
[Bill] And they were connected to RFC and Prudential. Both were probably the two biggest ones and then IndyMac sort of showed up with Countrywide. But when you look at it, non-agency became a thing as a result of over ADLTV jumbo limits. And then their connection was with mortgage insurance companies at the time. So they would outsource credit and all those things to MI companies who would then make the credit decision. Well, that industry sort of blossomed really in the late 80s, early 90s. And that was non-agency.
[David] It was. Yeah.
[Bill] And then in 94, in 1994, the Fed unbeknownst to me and probably everybody else in America raised interest rates seven straight times. So what ended up happening is it forced me to figure out what am I going to do? I go from about a billion a month of 30-year fixed rate loans in October of 93 to probably $100 million of HELOCs with RFC in January of 94. And then rates continue to ratchet up. So it’s a lot like I draw the corollary because it’s a lot like where we sit today. Interest rates, which were at two, three, four, have now ratcheted up to five, six and seven. There’s a couple of major differences in that we hadn’t we had never seen an inverted yield curve like we’ve seen today. I think probably ever for as long as we have seen it. So the 30-year fixed rate loan, it was much lower than the two-year. So we priced off the 10-year and the two-year. So it was inverted. And that drove this whole movement to where 30-year fixed rate loans were able to be done. And as you know, right coming out of 2007 and 2008, you ended up, we basically got rid of our second major superpower in mortgage, which was when interest rates went up, what did we do? We went to arms.
[David] Well right, exactly right.
[Bill] And we don’t have arms anymore. Arms today, we don’t have any of that. So I think when you came out of 07 and 08, because I think most of the problems that occurred then occurred because of the type of loan that we were putting consumers into. We started in fixed rates. We moved when interest rates went up to these 228s and 15 year fixed rate seconds. We combined those two and that alchemy and that elixir was not good because the consumer didn’t really understand it. I think coming when you look at today, right, I guess my point would be we’re sort of in a similar environment where the broker, the mortgage broker is going to continue to grow and the mortgage broker share is going to grow. And I think you’re going to see the share of non-QM or non-agency continue to grow as interest rates stay flat or high. And the rate in the non-QM non-agency market is relatively similar to agency.
[David] Yeah, it’s a great historical perspective. And there’s so many parallels. We could mean just go park there and go on and on and on to then and now, which really speaks to the biggest opportunity for non-QM and not agency over the next couple of years. I mean, what do you see as the potential growth of this product?
[Bill] Well, sits at, I mean, if you look at most data points today, sits at about, expanded credit sits at about 10%. So you’re looking at what I’m going to call agency plus at 90. And of what you’re seeing right now is the shift of the 90%, which was predominantly purchase becoming higher and higher percentage of refinance. And so I think, and if you follow 94 and you follow what happened after 94 and when you were at this period of what I’m going to say relatively high interest rates and a recession, I think what you get really at that time is you got the broker share, mortgage broker share at almost 50% and you got the share of non-agency, non-QM at 50%. Today we’re broker share coming out of the malaise of 07 and 08 was probably at 50, went to five. I think you’re going to see mortgage broker share go up and I think you’re going to see the non QM share go from 10% to probably 40 or 50%. So the real growth opportunity is probably in that product because that product probably fits better than agency and I’ll stay there, the agency model, if I could encapsulate it, would be agency is under a certain loan amount, primary occupant, owner occupied, single family home, purchase, employed borrower. I mean, that’s how it was built. The whole thing, it’s been around. Fannie Mae’s been around since the 30s, Freddie in the 70s. You know, Ginnie Mae is different, right, with FHA VA. But when you look at the agency market, that is the model. And so if you fast forward to today, you’re looking at a model that’s pretty much blown up because the things that agency doesn’t do well, it doesn’t do non-owner. It doesn’t do second home. It doesn’t really like refinance. It doesn’t do a second. It’s labeled then the two. I think coolest products that are financial engineered products, both the balloon and a HELOC as non QM. So what’s happened is all the things that people are doing more self-employed. have employed, non-employed, same people. have, we have passive income. We have influencers. have a world where the borrower has changed and the single-family residence has changed its use. It’s become more mixed use than ever. So, I mean, our parents, you’re my parents, our parents would burn the mortgage at the bowling alley or something, right? It was like a, it was an event. So today it’s a financial, it’s a financial engineered product. So it will continue and the emergence of flipping RTL, these rehab transition lenders. I would say you’ve got probably invest more investor loans ever done. You’ve got a whole channel that we watch on HDTV. You’ve all got your favorite shows and your favorite flippers. So I think I think it’s here to stay. My point in 80 when I in 1994, I got completely out of agency moved into non-agency and lived that until 05, when the world shut down, right? The whole product shut down. So I think my message to people today is, you could probably say you could have PTSD because of your experience through that period and you’re a little fearful. I think the better thing you should say is, a mortgage banking firm should have the capabilities to do agency and non-agency all the time. build it out one time and quit
[David] At all the time. Yeah. That’s it. Yeah.
[Bill] Trying to predict it. You should just be able to do it and it should be.
[David] I mean the ability to have agility in this market is so critical, especially for IMBs, independent mortgage bankers. and I think with one thing you said, the ability doesn’t mean that they should have to be required to do it, they have the ability to do that. But explain what you mean by the ability because a lot of people say, Well, I read the guides, but this is really coming in operational. There are some uniqueness’s, and in the way it’s underwritten, at least it was. But I’m we’re seeing AI. We’re seeing you and I both are close to Pavoa Agarwal and see what he’s doing. There’s some new technology that’s coming in. How does that play into being ready?
[Bill] Yeah, it’s funny because I actually think the agency business is about as paper intensive as it’s ever been. It’s actually the compliance nature of mortgage is so heightened that it’s almost ruined the business. And you can see that in cost to produce, right? Our cost to produce 15 years ago was 2000 bucks a loan. And you’d think with technology and with AI and with all these things and so our cost to do today is with all your help and all this work that we’ve done is only $13,000 a loan. So
[David] I know. Yeah.
[Bill] I think, I think the challenge, so the way I approach it with clients is you need to be able to be in lockstep. The key to mortgage is that the underwriting guidelines, in fact, you and I knew Frank Raines.
[David] Yeah, so absolutely.
[Bill] And Frank Raines at Fannie Mae used to have a great line where he said, you know, it’s a commodity, the 30 year fixed rate loans, a commodity, the key to really underwriting it is customizing the commodity so that when a consumer actually brings their income and assets and all these things to the party, that they see themselves in the guidelines. And that is not what we do. We basically say we have this box and everybody tries to get into that box. And I think what you see in non QM, which is pretty cool is that box is widening. That box is also built for specific types of borrowers, right? A HELOC. mean, look at what your feed figure and some of these folks have done with, with a HELOC. Look at what DSCR and discounted cash flow has done for investors and business purpose. One is designed for investors, the other is designed for equity out. Right? So, and I think the biggest growth that you’re going to have over the next couple of years is going to be, we’ve got records amount of equity. Clients aren’t going to all hit the bid at one time because interest rates aren’t going to just fall. So you’re going to be stuck with standard growing demand for equity because of the amount of equity that’s in each home. And that is one fundamental difference between this market and any market that we’ve ever seen.
[David] Yep, and the previous market. Yep. Yep.
[Bill] The second one is the change of the single family residence because you live in it, you office in it, you rent it. You ADU it, you retire in it. mean, it is by definition mixed use. Then if you add the borrower to this, which the borrower has fundamentally changed, you can see why, you you sort of. So the way I approach it with my clients is this is the most exciting time to ever be in mortgage because you can create products. You can create guidelines and rules that actually customize the commodity for…
[David] There you go. Yeah, it’s the skill to customize. And that’s one of the things that I admired about you. Maybe it’s your legal background, but you thought out of the box, probably as well as anybody I’ve ever met. We were always looking at what’s First Franklin doing. I didn’t realize you got the name because of the streets you’re on. That’s that’s that was information I just
[Bill] Yeah, I on. Yeah, I didn’t want to call it after me just in case it failed. But first, but Franklin Street was fine, which was good. It’s still there. It’s still there. Yeah.
[David] Yeah, it will it’s still there. And First Franklin has done so well. You shouldn’t look at it. one of the things one perspective you gave talked about the mortgage broker. It’s definitely on the uprise again. Will it ever, in your opinion, get to the levels that it was?
[Bill] I think so. I actually, look at, I just, you look at Nexa, you look at some of the bigger brokers and the mergers that have announced, mean, rare do you see 4,000 originators in one company. Brokerage, right? Brokerage was fragmented, right? There were, I think the other piece of it is if you look at retail coming out of, because the, people that we wanted to penalize in the last go round were banks and brokers. They went into the penalty box, right, and took it for everybody in 05, 06, 07, and 08. Clearly, their market shares went from 50. mean, if you think Wells Fargo, like our friend Mark Oman, Mark ran Wells Fargo, mean, he had a 40-some percent market share.
[David] It did. Yeah.
[Bill] And that today is probably one, two, right?
[David] Yeah, maybe.
[Bill] So you look at those folks going away and who, so over the last 20 years, mortgage, independent mortgage banks have gone up from probably 30, 40 % to almost 70. So is that going to continue? The one thing you and I can tell folks who are listening from our perspective is that if I took for the last 40 years. And if I took the top 10 lenders in each decade, they are different. And their genetic makeup, different. So whether you were Countrywide, Lomas and Nettleton, know, Saxon mortgage or different people, they were all leaders in the clubhouse at one time. So the one thing that you can be sure of, is that that mix is going to change. So I think banks are going to make a resurgence and small regional banks are really going to focus on mortgage. And frankly, they’ve got a huge advantage over an independent mortgage bank.
[David] They do. Yeah.
[Bill] And even if it’s just licensing, but forget cost of funds, know, the ability to warehouse themselves to do their own products and services from time to time. I think, I think for, and then brokers. So you’re going to see if we were today’s, let’s say 70% independent mortgage bank and the balance being somebody else, credit unions and credit unions, brokers, and banks, you’re going to see that shift to down. You’re going to see us lose our share. Independent mortgage banks down to 50. You’re going to see brokers grow and banks grow.
[David] Right. I that’s a very wide absolutely accurate prediction. I think you know you talked a little bit about PTSD, and then I think it comes from the risks that are there. One of the things that I mean, I knew you and I we were both in California owning mortgage companies at the time. Your success was just amazing. I looked at what you did and how innovative you are because of the products and the way you were innovating in the area of product creation. I think that’s a laugh that we have here. By people need to pay attention to the Bill Dallas School of getting out of your box and start thinking innovatively. And when things blew up, Bill, one of the things that I watched and respected about you so much, you went on television, you went on the public stage. We hadn’t with no reason for gain. Because a lot of them, you had some celebrated things that blew up along with everything else was blowing up. But what it respect made me you identify you as a leader in my mind. You didn’t just run and hide and go into the fabric. You went, dove in, and let’s look at this. Let’s look at what worked and what didn’t work. Let’s look at this and make intelligent decisions. The Spanish philosopher Santiago says we’re doomed to repeat what we failed to learn from history. And you were really on the forefront of trying to help people. Let’s draw some lessons from this so that when the next cycle comes, there will be another cycle. And we’ll repeat in a similar way that we don’t make those mistakes. So kudos to you for how you stepped out there. And did that. That was that you took some risks doing that. And I just gained so much respect. I said, I knew you as a business owner and then I watched how you handled that. That
[Bill] You know, it was it was it’s it’s it’s our responsibility, right? It’s it’s not mean if.
[David] It is well, it is, but not many many, many people run from that that aspect of responsibility because
[Bill] This was, I in our lifetime, right? I always said, who was I talking to? Casey, our friend, Casey Crawford once. And I
[David] Yeah. Just talking to them.
[Bill] Isaid, I’ve seen everything Casey and mortgage. I said, after COVID, I said, all right, I was wrong. I haven’t seen, I haven’t seen that yet.
[David] I haven’t seen that one yet, yeah.
[Bill] And I do think it’s, you know, products, I will stay with two things that you’ve said, right? One, thank you. I’ve That’s like you say, you just try to do the right thing. Our, my goal always is I don’t think we as originators and fulfillers for investors, we basically only have what the investors give us. So if I could mean, if I could draw the corollary between what I’m going to call it, let’s call it subprime and non QM. Right. So what’s, what’s interesting. And what’s different is that the amount of compliance that is required today, except for one product, DSCR, which is business purpose, right? You don’t see any. I see absolutely no corollary other than this is a bank statement question because customers weren’t qualifying back in 94, 95 and 2000 and in there. And they’re not qualifying today because guidelines in America have not changed in 100 years. So the consumer has massively changed. And what came out of 07 and 08 was we figured out a way to count all their liabilities and we’re going to count them, but we didn’t figure out how to count their income and we didn’t care to. So I think what you’re putting up with now is we’re now playing catch up. And I think product dev, mean, If there’s anything that’s wrong with most of my clients, it’s capital markets is all focused on agency and rolling out bond programs. And all it does is, you know, they just chase their tail. And I’ve never understood that we have like we have. We have one product, a 30 year fixed rate loan, and we have 500 different ways to do it. It doesn’t. How can we all, we all sell our loans at the same three places? How can we have any differentiation? Well, we got MSR buyers, have underwriting guidelines, have underwriting rules. Some people take more risks, some don’t. Big guys do this, little guys do this. We subsidize the rate. I mean, to me, there is zero value in a mortgage company that does that because we’re all the same. So we moved completely to non-agency because we could have a competitive advantage. Now I needed to have a big capital partner. You need to have deeper pockets and you just know that that market is not as liquid as the agency market. So you have to keep your head on a swivel in capital markets. But what I loved about it was it was, I created one set of underwriting guidelines to do 500 things which is the way it should work. And I just don’t know how mortgage companies continually roll out another set of guidelines, whether it’s in non QM or agency for the same stupid product. And then they wonder why their cost is like gargantuan. And, most of the capital markets guys that we talk to, they just say, you know, it’s like, it’s a storm, the Bastille moment or the Alamo. Right? Where we have no guns, we have no butter, we have nothing left and people are coming over the, you know, it’s like, and my view of that was when we shifted into non-agency, I was in control of the product queue.
[David] Yes, yes.
[Bill] And so what I don’t think the mistake that mortgage lenders are making today is they’re rolling out investors. because of a niche. So Deep Haven has this, these guys have that, ARK does this, Angel Oak does that. So you’ve got all these different investors and if you go to an S-FIG conference, there are so many people trying to do a non-QM loan that you could probably find a niche for anything. So these guys will do 4 million, these guys will do a DSCR up to 80, they’ll do this. And so I watch mortgage companies try to roll out niches and you will get your ass handed to you if you do this.
[David] Exactly right. That’s exactly right.
[Bill] So the fear I have for people is that they’re going to commit the same error that we did before. And if you follow what we did and what I would recommend you do today is the non QM business, the non agency business has to be a purchase business and it isn’t. It’s it’s a refi business
[David] Refinance product.
[Bill] And it’s a bad credit product. It’s a low LTV, high FICO, blah, blah. Right. OK. If you watch what first Franklin did, what only did it was all purchase. Why? Because mortgage is a purchase driven group of people.
[David] It is. That’s so true. So totally agree that the PTSD lives on from the subprime era that we saw. How do you help people overcome
[Bill] It’s really taking capital mark. Well, first, can’t. Liquidity, as you know, right, we are not depositories. And because almost all of our clients have X amount of net worth. Right. They have a production, they have this much book equity, they have this much cash. And then we all have to finance our assets and our closings through warehouse lending. Well, first, I think people don’t really understand the financial, until you’ve been at it a while and you’re relatively good size, the connection between warehouse, cap markets, finance and origination is unbundled somewhat. Right? So, my goal with my clients is to bring that group together in thinking because you’ve got to have the risk side covered. And what happened in non-agency this time was you want to fund a non-agency loan, cost you 10 points in your warehouse line to start. Well, you know what it costs today?
[David] Yep. Haircut haircut haircut went from ninety eight down to ninety.
[Bill] Today, you can get 102. Okay, it’s starting. So what you’ve got to do is you’ve got to be able to build a business where you’ve got liquidity, you’ve got cash, and you’ve got just like you and I would in our in our own lives. If you have to have assets left over in order to sustain yourself when the hiccup occurs. Generally speaking, the other piece. You’ve got to have good partners. I had big partners and they were good.
[David] Yeah. There and that you yeah, and you are brilliant. And how you did that, I mean, the big the you formed, I mean, one of the relationships you had was Merrill Lynch at the top. I mean, that was a brilliant partnership, and that’s a whole another podcast on how we want to do that. Because I want to stick with the non-QM as an emerging project. It’s people need to do that. And again, I don’t think there’s a better example of someone who thought out of the box and created the products that created a unique advantage for you. And there was a liquidity crisis that they hit the entire industry. This wasn’t hit a lender here and there. We saw some, remember the old 125 product? We watched that door come down close on that one pretty quickly. But there are close. And it’s just
[Bill] There are clues. There are clues everywhere, right? Yeah.
[David] having the wisdom and knowledge to have that experience. So, you know, how do you evaluate which non QM product, a capital partner a lender should add? Why would you advise?
[Bill] Yes. So it’s a great question, right? And so my view of it is like most of our warehouse banks require us to have a couple sources, right? Or we can’t do the long. So who do you who do you choose?
[David] Multiple sources. Yeah.
[Bill] I actually have put a lot of weight in my own work around a company called Maxx. And one of the reasons I’ve I like Maxx is they are They are a non-agency, they’re the only one in the world, a non-agency exchange. So what MaxX has is they have 35 investors over here. They’ve got them all to agree to one set of guidelines, one set of rules, one LLPA, you know, it’s a, it was a, and
[David] They commoditize that side of the business to a certain
[Bill] that is from chase on down, right? So you’ve got this list on this side, you’ve got sellers and sellers want access. Now they’re a little clunky in terms of how this works. And so what I tell my clients is first you start in warehouse and make sure you have enough liquidity in order to do this. And most of the clients, I see a lot of them go out into riskier products with not a lot of backstop. We have plenty of capital. Before I also see a lot of clients who start out with a capital partner. Right, which I think, okay, I see the benefit of both where you’ve got a partner like MFA or you’ve got a partner like Merrill Lynch or Blackstone or BlackRock or you pick them, right? So I think I think you first start in warehouse to make sure you’ve got the capacity and the ability to hold. Then, You have to then do you have the cash in order to do that? And then the third piece is you’ve got to revolutionize capital markets. And I think what I see overall is I think we’re moving from a product business to a solutions business.
[David] Mm-hmm. Well define what you mean by that. I mean when you say solution, I want to make sure that people our listeners understand that.
[Bill] So, so, it would be like you and I, we should probably both grew up. You know, I became a CEO because I was probably because I owned the business, but I was really a LO. Right. I understood. And traditional LOs always start or brokers start with can I get the borrower into a deal? And they out, they go out and search, then David shows up, David brings his own baggage. right of whatever he’s got to qualify with his income, his credit, his, you know, all these things, right? So the modern advisor starts with what is the borrower we’re trying to accomplish and what’s the best capital structure to get them in there. And what you’re seeing is a complete shift because this means you got to understand non QM plus DSCR plus a bank statement, plus a jumbo, plus a HELOC, plus a second lane, plus a bridge, plus a reverse, plus an investor. And whoa, this is a talented person. So rather than selling one agency product at a time with rates dropping and everybody doing refinances, you got to do this. So the winners won’t necessarily even care about rates. They’ll have the largest toolbox on the planet. So most of my work then goes to capital markets and saying, look, dude, you don’t wind up doing a non QM loan. You originate into it. It’s one of your products that help LO’s do something. And most of them look at me like, what? And then they don’t have there is no product development team inside of a capital markets group.
[David] Yeah. Yes.
[Bill] So we spend time with who is that person? How do they do it?
[David] That is such an important right. Yeah. That is such an important statement you just made. There is no one that has product development skills. They have trading skills, they manage risk as far as rate interest rate volatility, but as far as creating, looking at and creating products.
[Bill] They don’t do it. They’ve never
[David] They don’t do it.
[Bill] Done it. And so I think, you know, where does it go from here? Right. It’s it’s still early, very early. I have people tell me, my God, is commoditizing everything. Dude, it’s 10 percent of the market. It’s not even mean Heloc. my God, he likes that. It’s four percent of the market. So for. This is it. This is the tipping point.
[David] But but there is a tip, you know, you know the law of yeah, the law of diffusion of innovation. We look at how quickly things can change on that. And we’ve had those sudden shifts, those massive market shifts in the past. And I think we’re in there. So if I gave you an agency lender today and I told you, Bill, go and advise them to double their non-QM production in the next 12 minutes. What are the five things that you would recommend that they do?
[Bill] So we start with first, we start with, we’re going to change the way we think about, because mortgage bankers think about retail, wholesale, correspondent, servicing, blah, blah. Right. Stop. First thing, stop. Let’s, we are a platform. What we’re building is a platform and the platform should be able to do products, multiple products, multiple things. So we have to change the way we think from the beginning. The second thing is when you’re looking at agency, you have to say to yourself, are you willing to cannibalize agency? Because the only way you get loans from agency and the non QM is to eat it and bring it over.
[David] Yeah. Yeah.
[Bill] So how are you going to do that? What most of them do is retail is very slow, very hard and too cumbersome. And they’re all steeped into agency mostly, right? Unless you’re in California, New York, Chicago, maybe Florida, you know, where you’ve got places where there’s,
[David] The vast majority of the industry is steeped yeah, you’re right.
[Bill] There’s need for it. Right. so we start there. I give them a white paper. I’ve written a complete dossier and I can give it to you and share it with viewers or different people. But I wrote exactly what you just said. How do we build the next generation platform for agency lenders so that they can do all products? I said, look, we don’t want to be just non-agency, but how do we do both? And we start in cap markets and we start with product development. Do you have anybody in product development? You know, we do. We have people that do this and do that.
[David] Yeah. The torque is the predictable answer is no.
[Bill] And we begin to build that out. And then product, what does it do? Why does it exist? And if you think about really the four big ones, non-owner, cash out, rate and term, refi, second home. And then if you build any underwriting guidelines and nuances from DSCR to bank statement to all these things that it can do. All those things are available to you. I throw in balloons because IOs interest only loans and HELOCs are all non QM. So I then walk them through a product rollout for let’s start with HELOCs. Why? Because everybody’s got a bunch of equity and nobody does it very well.
[David] True.
[Bill] Second, then do so you move from there to IOs. I think the one thing that we are going to get is our interest only. You are already seeing banks do it. I most of my clients are getting killed in big markets by major money center banks that will do a five year or a seven year loan to a private client at five and a half. And yet you’re having to fund a 30 year at six and three quarters or something like that. Right. So we’ve got to create an IO and then, from there, I take them into what I call the next generation non QM. And I start with just the two easy ones because I start with a HELOC and I own, and then I’m moving them mostly to a first mortgage HELOC. Which nobody’s ever done thought of personally. The only loan I have on my house is a HELOC because I want to, I don’t want to, I want to advance when I want to advance. Right. And Heloc have got the same PTSD that non QM has. Right. And, by the way, most warehouse lines don’t know how to fund seconds. Don’t like seconds. Right. So I think you start with this product queue, and then I work my way to one set of underwriting guides. And you have to then force your invest.
[David] That is so critical right there because it it big brings the simplicity back in what you fell. Yeah.
[Bill] If you don’t, you will fail. Cause if you roll out 15 different investors in non QM, you’ll repurchase half of them. You’ll have all these problems with the other half. There are more issues of loans that don’t fit and then where do you sell it? Okay. All those things are bad. So that is sort of the queue, but it starts with adding product dev to cap markets.
[David] Yeah, yeah, I’m gonna encourage our listeners to reach out to you, Bill. We’re gonna get your contact information and share that here in just a minute. I’d love to have that white paper attach it to this podcast so people can download that if you’re if you’re fine with that. We’ll get that. If you can send that over to us, we’ll make sure we include that in there. Again, the purpose of this podcast is help people do intelligent things in this business, help people grow and make it survive. And because we have some companies that we’re seeing the biggest merger rate of mortgage companies. Why? Because no innovation. They don’t know what to do, they’ve lost hope. But when you lose hope. You just you just sell you’re looking for an exit and you’re not thinking forward. And there’s I agree with you, we are have the best opportunities, the best days, potential days for mortgage lenders is ahead of us, not behind us. The best.
[Bill] I just think that if the low rate calvary isn’t coming to save us, which it isn’t,
[David] It isn’t.
[Bill] then your growth depends on a strategy on higher rates and cash out non-owner, the things that are actually working. I think for 15 years coming out of the malaise, right. I came back in with skyline. And created FOA took them public. You know, it was a it was interesting, right? Because one of the things like you were saying. One of the groups that we brought in was a company called Afterburners, and I remember those guys. Yeah,
[David] Yes, yes. I remember absolutely.
[Bill] And so John Duhadway and Bruce Dickinson and I who were the we sort of were the brain surgeons that own it and built the relationship with with Merrill. One of the things that we did was we brought them in and they were very good with us of saying, look, we’ve never seen an industry like you. You guys all run from the seat of your pants. We are all about redundancy, reciprocity, making sure we always have contingency plans and all of that, because we at Afterburners are jet. We are top gun guys.
[David] Exactly right.
[Bill] And so. One of the things that stuck with me and our team was debriefing after an event.
[David] Yes. The importance of debriefing. There is there is a there is Angels video, blue angels video that to a stand in Seattle. I lived in Seattle when the blue angels did it over there and they did a debrief and there’s a video on it, and I use that today. How many people are doing an intelligent debrief? And there’s and then it’s not the macro mistake, it’s the little micro mistakes that are made that can absolutely be fatal when you’re flying that close to
[Bill] No, you know, and it can be like you said, could be, excuse me, it could be big or little. After 05, I closed OwnIt, which is my second business after first, I was done with First Franklin National Citibank at bottom. They sort of kicked me out and the same investor group called me back and said, hey, would you let’s do this again? I said, well, We’re living on borrowed time. Because in my view, I think home prices have gone like this, incomes have gone like this. We’ve got a short period of time to make hay. Right. So we bought a Oakmont mortgage and we began this process. And in about 18 months, we had monetized. had our investors had done so well in October of 2005, we basically made the call to shut down. And it wasn’t me. It was all my people in a room talking about this. And so we made this decision. We’re where we caught what was it? The implodometer, right? So we were early to the we were like number three on the implodometer and we got out. We were done. I actually returned like 40 or $50 million more to all my shareholders, but we were done and out right before the world sort of cratered. One of the things that our group did going back was we debriefed in 2007, six, seven, six, seven, is we, is we debriefed the situation. It was the most interesting thing that I think I’d ever been through.
[David] Wait, if we could have videos of that that that those debrief feedings
[Bill] What was cool was we ended up that debrief became my strategy for a next generation mortgage company, which was Skyline. And that served me for the next 15 years. So what I would say to our listeners for 15 years, our industry has become incredibly good at manufacturing agency mortgages and highly in a highly compliant environment. The next decade is about becoming incredibly good at solving financial problems, offering products and services that are outside of the box because the old model of agency is no longer sufficient. Now you’re going to it. Everybody says, you know, can just agency safe and we can do all these things. Look guys, fit the, had the largest fraud detection business in the space. The number one issue in fraud detection and agency is almost always occupancy.
[David] Yes.
[Bill] The second is income and assets. But if you look at occupancy, that is the next big, I think, crater. And so I think you have to have products and services that allow you to put clients into these boxes instead of trying to put them into one box that really doesn’t fit.
[David] One box. Yeah, over there. Bill, what a great way to wrap up this interview because you just gave a real I mean, you just created a window into the future. I’m so grateful for our time together. I’m so grateful for the friendship that has grown out of us us Californians that have we’re building businesses. Again, I want to say thank you for the innovation you brought to our industry, the leadership you brought to our industry, and you continue to do so. How can people get a hold of you? People more your phone should blow up.
[Bill] I don’t know. It’s like you. mean, look, they can call. Look, I am Dallas capital. Dot com. Right. Or like I said, when I took over it at Skyline and Finance of America, right over time, when I came in, I go eight five three nine seven four six eight. Look, that’s my cell. I’m not that hard to find. Right. Obviously, I got all these folks on the planet that trash call you all the time. But I think one of the things it’s been like for you and me, we are lucky to be able
[David] We are very glad.
[Bill] To help you. Our goal, my goal is to help you build a business that has value. And like even now with my clients, I’m looking at, I mean, if you haven’t started looking at 27 and 28 of where you want to end up,
[David] Exactly right.
[Bill] You’ve got to start today. Forget AI, forget the things that are noise into what’s happening. You have to figure out how you want to build an agency, how you want to build a platform that does loans instead of I’m an agency lender, I’m a non QM lender, I’m doing this. And if you can figure out how to get this one set of guidelines working. Then you’ve got to figure out, the customer, which is a whole, mean, we could do a whole strategic on the top of the funnel. What’s happened to the borrower? think AI and internet and change and the ability to democrat, the democratization of MLS and the, and the ability for consumers on Redfin and Zillow and all these different things to just bang, you know, look at a code, pick up, get a listing. Look, these people are coming at us. They’re very smart. They know something. They know a house, they know an area, but they don’t know how to do this, which is our superpower as originators, right? So I don’t
[David] Exactly right. Yeah. I get I get a chuckle, I get a chuckle. I’m sure I don’t know if you get this, but I mean I just turned 76. A lot of people go, man, you old guys have just got to retire and go away. And I go, No, no, no, no. I think we’ve got some experience you may want to learn from over the years, because otherwise you’re going to be running into some walls that we’ve we either narrowly escaped out of and ourselves and may have bumped into a few of them. But Bill, thanks so much for being here. I wish you and Bev the best in your family. I just love all.
[Bill] You’re welcome. You too.
[David] The things you’re doing beyond that. the Christian schools that you’re supporting. there’s just so much that you’re doing to give back to with the success that you have. And it’s good to see you staying healthy and young. You’re living up in Minnesota and Las Vegas, the two favorite places. I mean, I grew up in Minnesota. I’m now in Knoxville, but it’s beautiful. I love spending time with you, and thank you so much for being here. And
[Bill] You’re welcome.
[David] listeners, pay attention to this. He gave you your cell phone number, listeners.
[Bill] Yeah.
[David] Go to the website first. Listen to this podcast. Don’t just pick up the phone and call them and get to the white paper
[Bill] I’ll send you the white paper now so you can take.
[David] and then read that. Read that. And then after you read that, then make the phone calls if you’re interested in learning more. You should learn want to learn more. Bill’s onto something really big here. Thank you, Bill. Thanks so much for being here. You bet. Blessing.
[Bill] Thank you, Dave. All right, see you buddy.
[David] God bless.
[Bill] You too, bye.
Important Links:
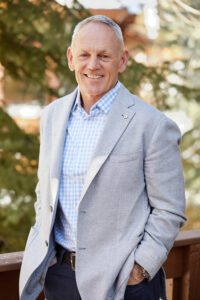
Bill Dallas is Chairman of Dallas Capital, a strategic advisory firm shaped by more than four decades of building, scaling, acquiring, and transforming companies across mortgage lending, fulfillment, and fintech. Known for stepping into complex situations and driving meaningful change, Bill has founded, led, and advised numerous industry-defining organizations.
Over his career, Bill has been responsible for the leadership and growth of companies including First Franklin, Heritage Bank of Commerce, Ownit Mortgage Solutions, InterThinx, MindBox, Skyline Home Loans, Cloudvirga, and Finance of America Mortgage. He brings this depth of experience to CEOs, boards, and leadership teams, helping them anticipate what’s next and execute with clarity and confidence.
Bill earned a Bachelor of Arts degree, magna cum laude, from Bowling Green State University and a Juris Doctor from Santa Clara University School of Law. He has been recognized as one of Bowling Green’s Top 100 Graduates, founded the university’s Center for Entrepreneurial Leadership, and was inducted into its Business Hall of Fame.
Beyond his professional work, Bill founded Oaks Christian School and serves as a board member and Chairman Emeritus of the Board of Trustees. He lives in Las Vegas with his wife, Bev, and together they have five children and four grandchildren.